
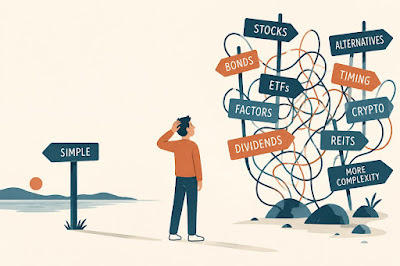
The difference between useful diversification and unnecessary complexity is not how many investments we own, but whether each additional decision serves a clear purpose. Vanguard’s 2026 research on the power of diversification adds an important distinction: broad exposure helps capture the small minority of stocks responsible for a disproportionate share of long-term wealth creation, but adding funds with overlapping holdings does not necessarily add meaningful diversification.
There is a particular kind of complexity that develops gradually in an investment portfolio. It rarely begins with a deliberate decision to build something complicated. More often, it emerges from a sequence of individually reasonable choices. An investor starts with a broad equity fund, adds bonds to reduce volatility, introduces a regional allocation for diversification, and eventually becomes interested in factors, commodities, alternative strategies, or individual companies. Each addition has an explanation, and some may genuinely improve the portfolio. Yet after several years, the overall structure can become difficult to describe, even for the person who built it.
As the SEC’s investor education guidance notes, diversification depends on underlying exposures, not simply on the number of funds held. The problem is not necessarily the number of holdings. A portfolio containing twenty securities can be economically simple if those securities serve a coherent purpose, while a portfolio containing only three funds can conceal significant concentrations or overlapping risks. Complexity becomes problematic when the investor loses sight of the relationship between individual positions and the objectives they are supposed to support. At that point, the portfolio is no longer the expression of a clear investment philosophy. It becomes a record of decisions made under different circumstances, with different expectations and sometimes contradictory assumptions.
This distinction matters because portfolio construction is not simply an exercise in selecting assets. It is also the design of a decision-making system that must remain workable through changing markets, personal circumstances, and emotional conditions. An allocation that appears reasonable in a spreadsheet may become difficult to maintain when several components behave unexpectedly, particularly if the investor has never established why those components belong together.
Why Complexity Is So Attractive
Financial markets offer an almost unlimited range of investment ideas. Investors can pursue geographic diversification, factor exposures, sector opportunities, income strategies, inflation protection, systematic trend following, and many other approaches. The availability of these instruments is a genuine advantage. It allows portfolios to be constructed around objectives and constraints that would have been difficult to address with a narrower investment universe.
However, greater choice also creates a subtle problem. The ability to make an additional decision can easily be mistaken for the necessity of making it. When an investor encounters a compelling strategy, the natural question often becomes whether it should be added to the portfolio, rather than whether the existing portfolio has a problem that the new strategy would solve.
This tendency is reinforced by the way investment information is presented. Every asset class has periods of exceptional performance, every strategy has favorable historical environments, and every specialized fund can be accompanied by a persuasive explanation of why its exposure deserves a place in a diversified portfolio. Considered individually, these arguments may be reasonable. Considered collectively, they can encourage an accumulation of positions without a corresponding improvement in the portfolio’s underlying design.
There is also a psychological dimension. Investment outcomes are uncertain, while research and portfolio adjustments create a visible sense of progress. Reading another analysis, identifying another opportunity, or refining an allocation can feel productive because these activities produce immediate results in the form of knowledge and decisions. The actual benefits of those decisions, however, may remain uncertain for many years.
This does not make research or active portfolio design inherently wasteful. Understanding investments is valuable, and thoughtful adjustments can improve a portfolio. The difficulty is distinguishing between decisions that change its economic characteristics and decisions that mainly satisfy the desire to do something. The first may justify additional complexity. The second often creates obligations without providing a meaningful advantage.
Diversification Is Not the Same as Accumulation
One of the most common justifications for adding investments is diversification. Yet diversification is a property of the portfolio as a whole, not a simple function of how many positions it contains. What matters is the exposure to different economic risks, the relationships between assets, and how those relationships behave under changing conditions.
Owning several equity funds that track similar markets may increase the number of holdings without materially changing the portfolio’s risk. A global equity fund already provides exposure to thousands of companies across countries and industries. Adding a collection of regional or thematic funds can be useful when the investor deliberately wants different weights, but those additions do not automatically create new sources of diversification.
Conversely, an additional strategy can introduce genuinely different behavior even if it makes the portfolio more complicated. Certain systematic approaches, for example, may generate returns through mechanisms that differ from conventional equity and bond exposures. Their usefulness depends not simply on historical returns but on how they interact with the existing portfolio, particularly during periods when traditional assets struggle.
This is why a blanket preference for the smallest possible number of holdings can be misleading. Simplicity should not become a rule that prevents investors from considering meaningful improvements. A portfolio concentrated entirely in equities may be straightforward to understand, but that does not mean it is appropriately diversified for someone who depends on the capital to finance living expenses.
The relevant question is whether an additional investment changes something important. Does it reduce dependence on a particular economic environment? Does it address a specific risk? Does it improve the portfolio’s ability to support withdrawals or withstand prolonged market declines? Or does it merely divide an existing exposure into smaller pieces?
These questions are more useful than counting funds. They shift attention away from the appearance of diversification and toward the economic function of each component.
The Cost of Maintaining a Complicated Portfolio
Even when an investment has a plausible theoretical benefit, implementing it creates practical obligations. The investor must understand how the position works, determine an appropriate allocation, establish expectations, and decide how to respond when actual performance differs from those expectations.
These obligations are often underestimated because they are not immediately visible. Fund expenses and transaction costs can be measured, but the attention required to maintain a strategy is more difficult to quantify. So is the behavioral cost of introducing additional opportunities for comparison, disappointment, and intervention.
Consider two investors with portfolios designed around similar long-term objectives. The first uses a relatively simple allocation of broad equity and bond funds. The second adds several specialized strategies intended to improve diversification or risk-adjusted outcomes. The second portfolio may be economically superior under certain assumptions, but realizing that advantage requires the investor to understand why some components may underperform for extended periods.
A strategy designed to provide diversification will not necessarily produce positive returns whenever equities decline. Its relationship with other assets can vary, and its benefits may emerge only over particular market environments. If the investor expects consistent protection, temporary disappointment can lead to abandoning the strategy precisely when its long-term role remains relevant.
The complexity of a portfolio therefore has to be evaluated alongside the investor’s capacity to maintain it. A theoretically attractive allocation that requires constant interpretation, frequent intervention, or unusually strong conviction may be less suitable than a simpler alternative with slightly less appealing historical characteristics.
This is not an argument against sophisticated investing. It is an argument for recognizing that implementation is part of the investment strategy rather than a secondary detail. The investor’s behavior determines whether the theoretical benefits of an allocation can actually be captured.
Portfolio Design and the Experience of Loss
Traditional portfolio analysis frequently emphasizes long-term returns, volatility, and maximum drawdown. These measures provide useful information, but they do not fully describe the experience of holding an investment strategy through difficult periods.
The duration of losses is particularly important. Two portfolios can experience similar maximum drawdowns while requiring very different amounts of time to recover their previous values. For an investor with a long horizon and stable income, this difference may be manageable. For someone approaching retirement or relying on portfolio withdrawals, an extended recovery period can have more significant consequences.
This is where diversification and portfolio complexity deserve a more careful examination. An additional asset or strategy should not be judged solely by whether it improves a historical return statistic. Its potential contribution to the depth and duration of losses, the stability of withdrawals, and the investor’s ability to remain invested may be equally relevant.
A portfolio that reduces the severity of certain declines can provide benefits beyond the immediate preservation of capital. Smaller losses require less subsequent growth to recover, and shorter periods of financial uncertainty may reduce the temptation to make disruptive changes. These effects can influence the sustainability of an investment plan even when differences in long-term average returns appear modest.
At the same time, risk reduction should not be assumed simply because a portfolio contains more components. Assets that behave differently during ordinary market conditions can become highly correlated during a crisis. Some strategies introduce risks that are less familiar or less visible than conventional market volatility. A complicated allocation may therefore create a false impression of resilience if the investor does not understand the circumstances under which its diversification is expected to work.
The objective is not to eliminate losses, which no realistic portfolio can guarantee. It is to understand the nature of the risks being accepted and to construct an allocation whose behavior remains compatible with the investor’s financial needs and psychological tolerance.
When Additional Complexity Is Worthwhile
There are legitimate circumstances in which a more sophisticated portfolio is justified. Tax considerations may require separating investments across accounts or using particular instruments. Investors approaching retirement may need to coordinate liquidity, bond maturities, and withdrawal requirements. Others may choose systematic strategies or alternative sources of return to reduce dependence on conventional stock and bond markets.
These decisions can create additional work, but complexity is not necessarily inefficient when it serves a clearly defined objective. A portfolio designed to finance spending over several decades may reasonably require more structure than one intended solely for long-term accumulation.
The important distinction is between complexity that solves a problem and complexity that creates the appearance of a solution. Adding a strategy because it addresses a documented weakness in the existing portfolio is different from adding it because its recent performance is attractive. The first decision begins with the portfolio’s needs. The second begins with an investment product.
This suggests a practical standard for evaluating changes. Before introducing a new position, the investor should be able to explain what function it will perform, what evidence supports that function, and under what circumstances it might disappoint. The expected benefit should be sufficiently meaningful to justify the additional monitoring, costs, and decisions that the position introduces.
The same reasoning applies to existing holdings. An investment should not remain in a portfolio merely because it once appeared attractive or because selling it would require acknowledging that the original thesis has changed. A coherent portfolio is not necessarily static. It can evolve as circumstances and knowledge develop, provided that changes are made within a consistent framework.
There is also no universal level of complexity that is appropriate for everyone. Some investors genuinely enjoy researching strategies and possess the experience and discipline to manage them effectively. Others prefer an allocation that demands little attention beyond periodic review. Neither approach is inherently superior. What matters is whether the portfolio’s design is compatible with the investor’s objectives, abilities, and willingness to maintain it.
From a Collection of Investments to a Coherent System
A useful way to examine an existing portfolio is to temporarily ignore the individual products and consider the roles they perform. Rather than beginning with ticker symbols, the investor can think in terms of growth, stability, liquidity, inflation sensitivity, and exposure to different sources of return.
This perspective often reveals whether several holdings are performing essentially the same function or whether an apparently unusual position contributes something genuinely distinct. It can also expose contradictions, such as combining a long-term investment philosophy with frequent tactical changes driven by short-term market narratives.
The exercise is not intended to force every portfolio into a conventional allocation. It is meant to establish a relationship between objectives and implementation. If the purpose of an investment cannot be explained without referring primarily to recent performance or a persuasive market forecast, its role may deserve reconsideration.
A coherent system also requires rules for managing uncertainty. Investors cannot know in advance which asset class will perform best over the next decade or which strategy will provide the strongest protection during the next crisis. They can, however, establish how much risk they are prepared to accept, how they will review their allocations, and what conditions would justify a meaningful change.
These decisions reduce the need to continually reinterpret the portfolio in response to new information. They also make it easier to distinguish between a strategy that is behaving as expected under unfavorable conditions and one whose underlying assumptions may no longer hold.
Simplicity contributes to this process by reducing unnecessary decisions, but coherence is the more important objective. A portfolio with several complementary components and a clear operating framework can be easier to manage than a smaller portfolio whose purpose and rules remain ambiguous.
A similar distinction emerges when considering portfolio rebalancing. The objective is not to follow a mechanical routine, but to understand which risks have changed and whether the portfolio still reflects its original purpose. This relationship between simplicity, discipline, and risk is explored further in Portfolio Rebalancing — Smart Risk, Not Routine.
Ultimately, the value of an investment portfolio lies in its ability to support a life outside financial markets. Its structure should reflect the capital required, the risks that can be tolerated, and the degree of attention the investor reasonably wants to devote to managing wealth.
The goal is not to construct the simplest portfolio possible, nor to pursue sophistication for its own sake. It is to find an appropriate balance between the benefits of diversification and the costs of maintaining additional complexity.
Every new investment should earn its place by contributing something meaningful to that balance. If it does, the complexity may be justified. If it does not, the investor may be better served by a portfolio that asks fewer questions and makes its underlying purpose easier to understand.
Leave a Reply